

If you work with clients outside the UK, you may wonder whether to charge VAT — and if not, what to include on your invoice.
This guide explains how VAT works when you sell services or digital products to overseas clients (rather than physical goods). Since Mighty is built for service-based businesses, we’ll focus on how VAT applies to freelancers, contractors, and digital companies working with overseas customers.
We’ll break down how the place of supply affects whether VAT is charged for both business (B2B) and consumer (B2C) clients.
The place of supply:
The place of supply is the rule that decides which country’s VAT applies.
For services, HMRC determines the place of supply based on where your customer belongs:
- If your customer is a business, the place of supply is where they’re based.
- If your customer is a consumer, the place of supply is usually where you’re based, unless the service is digital — then it’s where the consumer lives.
This rule underpins everything that follows.
Invoicing overseas businesses (B2B)
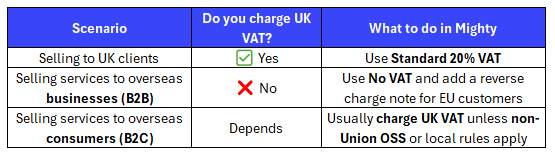
If your customer is a business outside the UK, you don’t charge UK VAT because the place of supply is where your customer belongs.
Therefore, when raising sales invoices, select ‘No VAT’ as the VAT category. This simply means the sale is outside the scope of UK VAT so no VAT is added or reported.
If you’re invoicing an EU business customer, you should also include a note on your invoice such as:
“Reverse charge: customer to account for VAT in their country.”
This tells the client that they need to self-account for VAT in their own country. Other than adding this note, there’s nothing else you need to do. For non-EU business customers, you don’t need to include a reverse charge note.
Invoicing overseas consumers (B2C)
If your customer is not a business (for example, an individual abroad):
- For non-UK, non-EU consumers, you usually charge UK VAT, because the place of supply is the UK.
- For EU consumers, digital or electronic services are subject to local VAT in the customer’s country, so either:
- Register for the non-Union OSS in an EU member state (commonly Ireland or the Netherlands), or
- Register separately for VAT in each EU country you sell to, which can quickly become admin-heavy!
If you mainly sell digital services or subscriptions directly to overseas individuals, it’s worth checking with us to confirm whether non-Union OSS registration applies to you.
Buying from overseas suppliers?
If you’re on the other side of the transaction, buying software or services from abroad, you may need to apply the VAT reverse charge instead. You can read more about that here.
Summary:
If you have any questions with this, please contact your dedicated accountant or email support@mightyaccounting.com.


